Advice first. Products second.
Anyone can ship you a terminal. Our consultants read your statements, sit in your operation, and recommend the smallest configuration that fixes the problem — including telling you to keep what already works.
Our consultative approach →Software and hardware to run the whole operation
Clover® POS
Station, Mini, Flex and Go hardware with the Clover app market — and dual pricing built into the checkout flow.
Payroll & Benefits
Hourly, salaried and contract staff on one run, with withholding calculated, deposited and filed.
Banking & Treasury
An account with its own details, cards you issue per person, and limits you set by amount or category.
ACH processing
ACH.com for recurring debits, invoice collection and payouts — cents per transaction instead of card rates.
Stop paying card fees out of your margin.
Dual pricing shows a cash price and a card price at the shelf and on the receipt. Customers who pay by card cover the processing cost; customers who pay cash pay less. Most merchants who switch see their net processing cost fall close to zero.
See if it fits your businessA card-brand approved program, set up the way the rules require.
Surcharging is permitted — but only inside a specific set of card-brand rules, and only in states that allow it. Most of the trouble merchants get into comes from a terminal switched on without the registration, the caps, or the disclosure. We run the whole program so yours holds up to a card-brand review.
Three ways into the Payvori network
An account that knows about your card processing
Funded within minutes of batch close
The month-end that does itself
Shaped around how you already work
Tools most small business accounts do not give you
Every payment type, one balance
Funds are held in a secure pass-through FDIC-insured account, and every common rail is supported both directions. Linking external bank accounts is supported; fees apply.
Bank-grade, and audited like it
Pass-through FDIC insurance is subject to FDIC rules. Fees apply to linked external bank accounts.
Faster funding changes what you can do
Paying staff and suppliers sooner improves retention and puts early-pay discounts within reach. Tell us your batch volume and we will show you the timing difference.
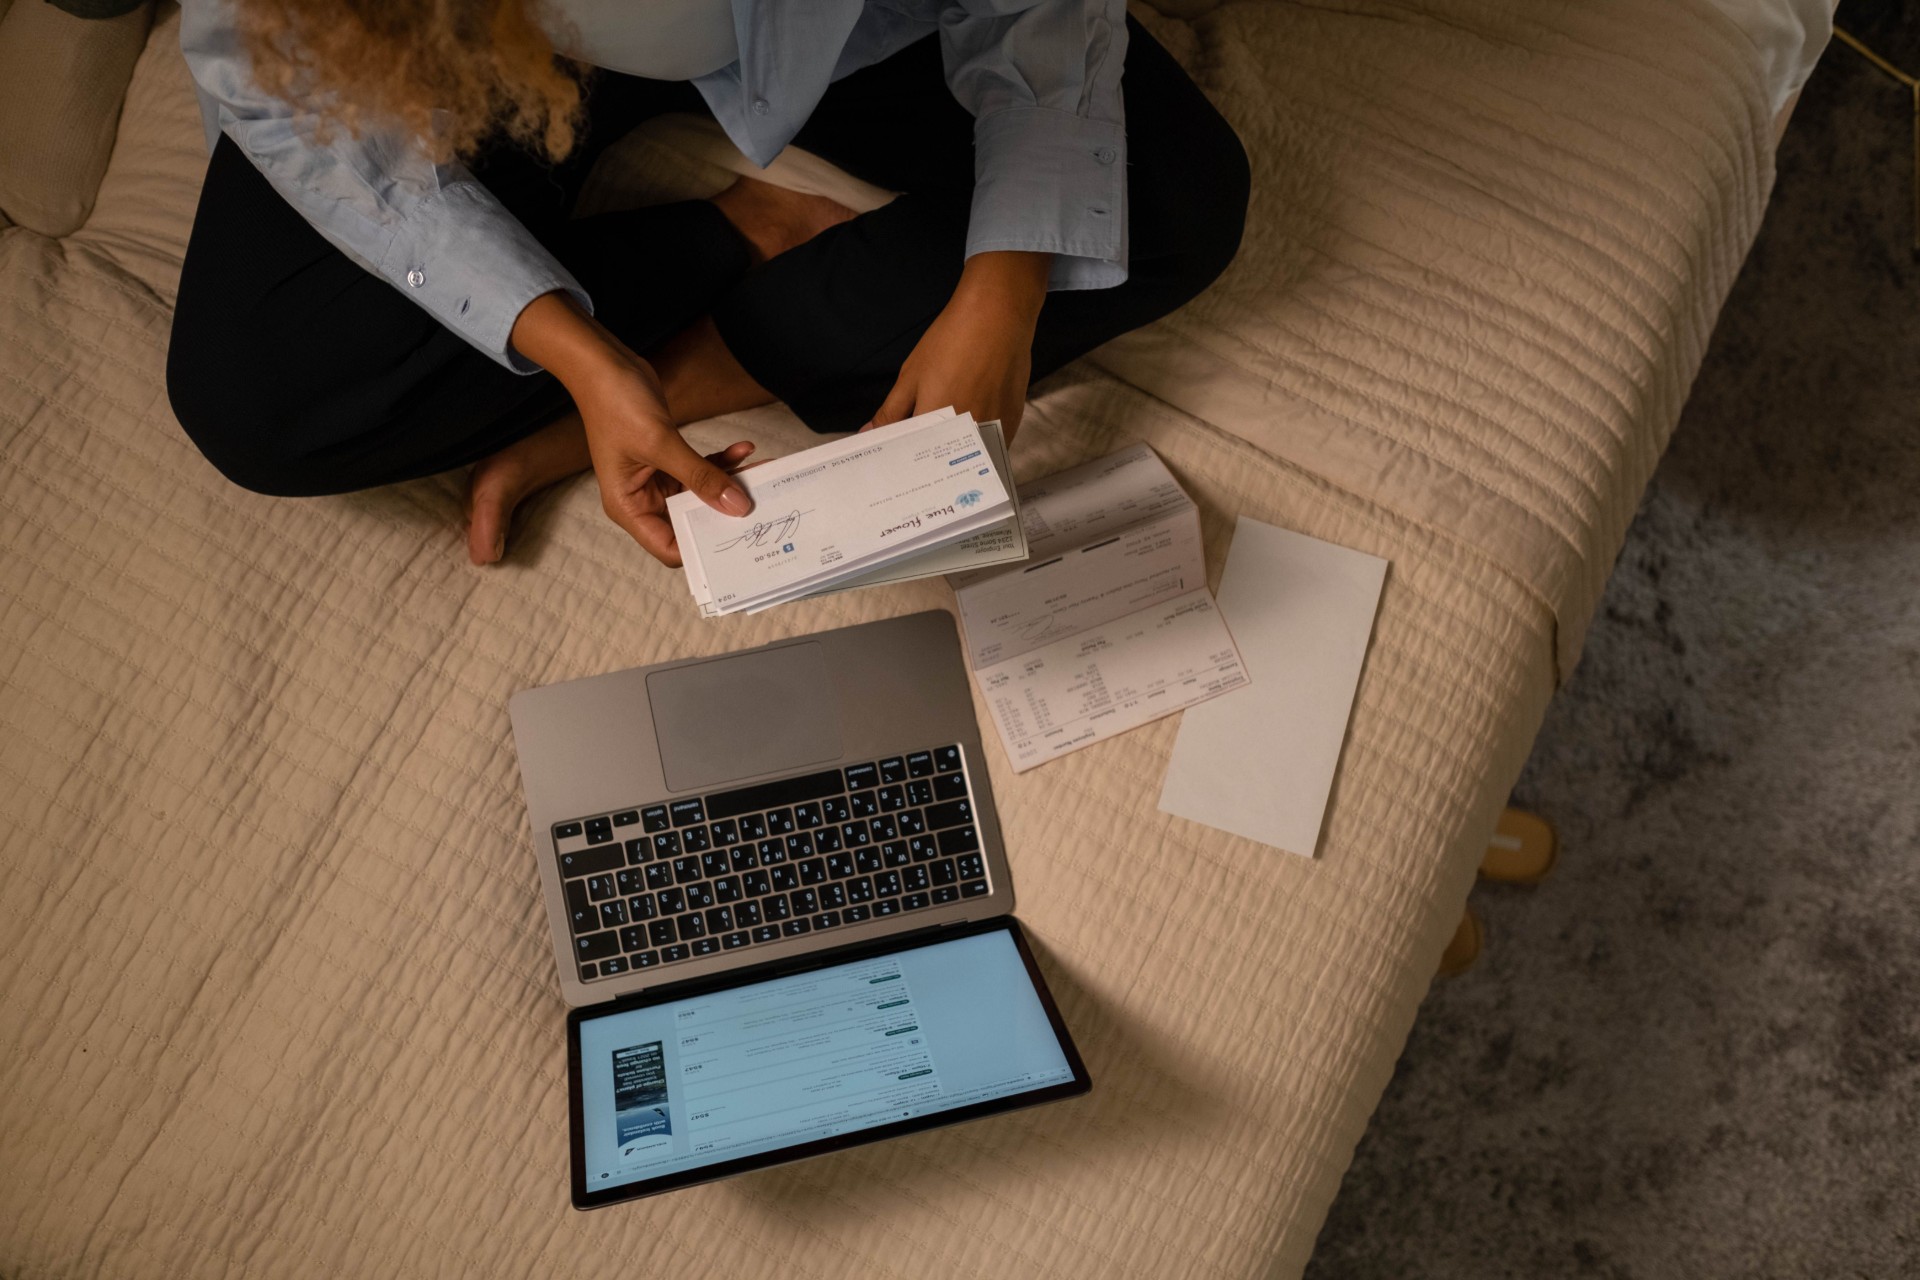
Not all ACH processors are the same
Tier 1 processor with a Fed terminal on site
One of only a handful of processors in the country entrusted with a Federal Reserve terminal on premise. In practice that means earlier return information, better exception handling, and the latest possible cut-off times.
Accredited ACH Professionals on staff
Multiple AAP-certified specialists, which matters the day a return code needs interpreting or NACHA rules change and someone has to tell you what it means for your file.
Real-time visibility
Advanced online reporting as transactions happen, with checks and balances across every batch so you can measure results rather than wait for a statement.
When a percentage is the wrong shape of fee
On a $40 ticket, card pricing is fine. On a $4,000 invoice or a monthly membership, a percentage of the total starts to cost real money for a payment that took no more work. We usually run ACH alongside cards and let the customer pick.
What you can do with it
Key entries by hand or hand us the file
Small originators work out of the virtual terminal. Higher-volume shops and software platforms push NACHA or CSV files and pull results back automatically. Both run on the same platform, so you can start in one and grow into the other.
Work entry by entry, in the browser
Automate the whole cycle
Debits are where the exposure lives
Pulling money from someone else’s account carries risk a card payment does not. The controls and the people behind them are the reason to care which processor sits underneath.
See what moving off cards would save
Tell us your average ticket and how much of your volume is recurring. We will show you which payments belong on ACH and which are better left on card.
Three things that make the difference
Worry-free compliance
Tax calculations, withholdings and filings are handled by the platform — keeping you compliant with federal, state and local rules, and reducing the risk of errors or penalties.
Easy onboarding
Setup guides you step by step and takes minutes, with no technical expertise needed. Data imports cleanly from your current provider, and we are on the call while you switch.
Connected to the rest
Payroll shares data with your other products, so there is less manual entry and less to reconcile. Card deposits and wages sit in the same view.
Everything a payroll run needs
Hourly, salaried and contract staff on one run, with the filings and the paperwork taken care of behind it.
Move at a quarter boundary and nothing breaks
Payroll is the one product we would rather you moved on our timetable than yours. Switch at a quarter end and year-end filings stay clean; switch mid-quarter and someone spends a weekend reconciling. We will tell you which date to pick.
Ready to stop dreading payroll day?
Tell us your headcount and how people are paid. We will show you what the run looks like and what it costs.
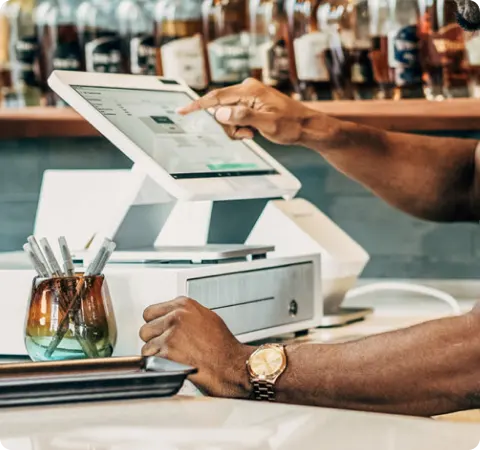
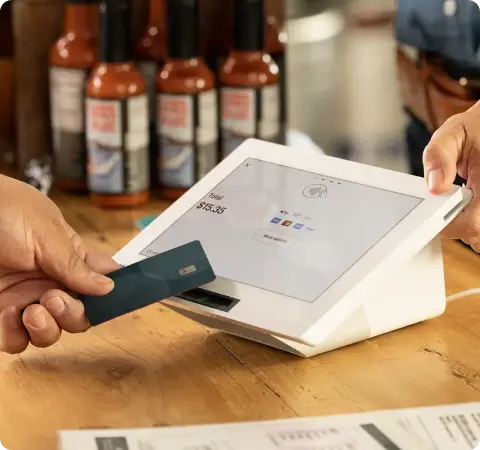
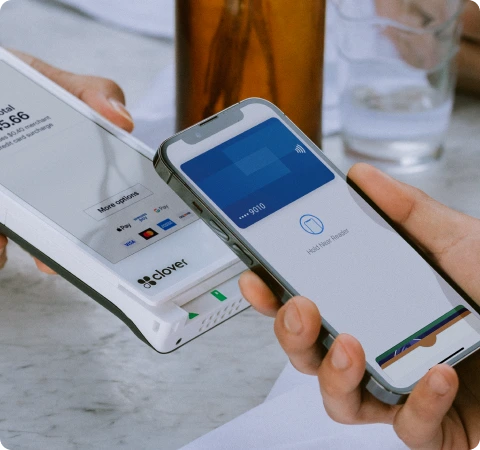
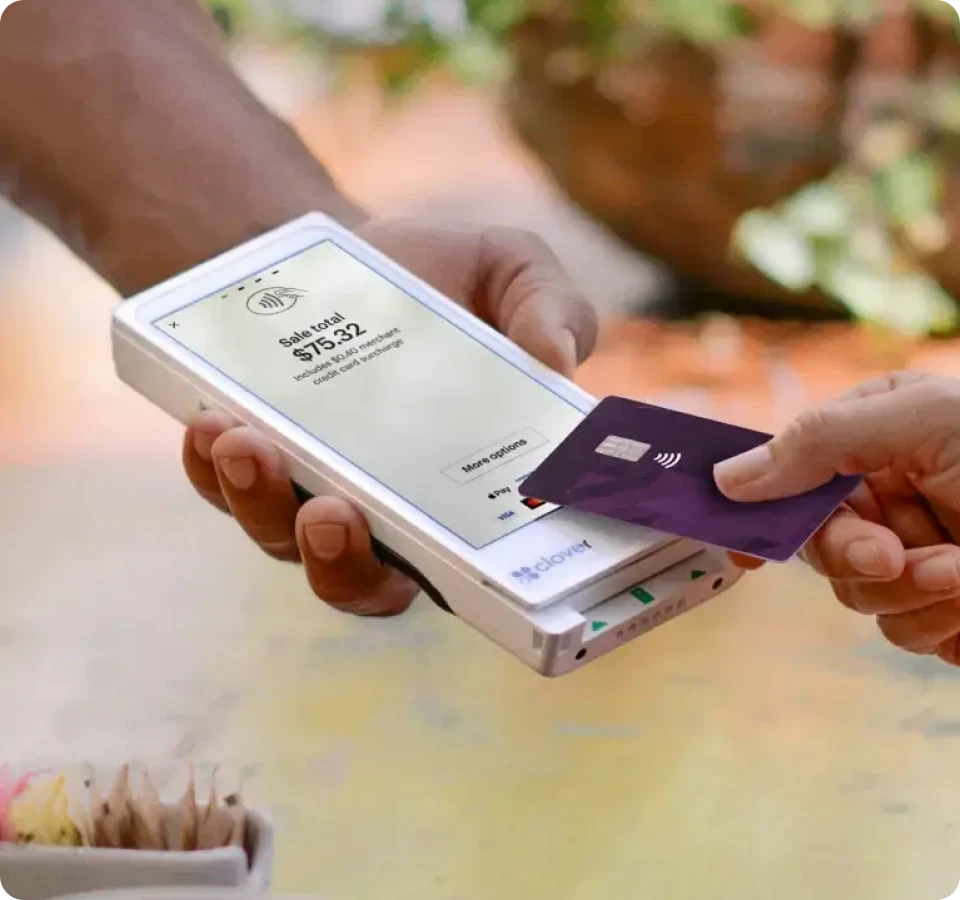
Current-generation devices
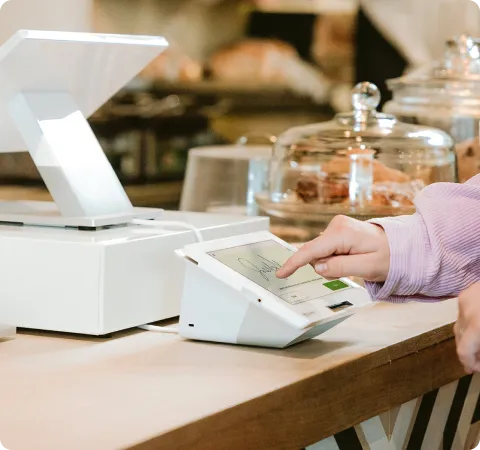
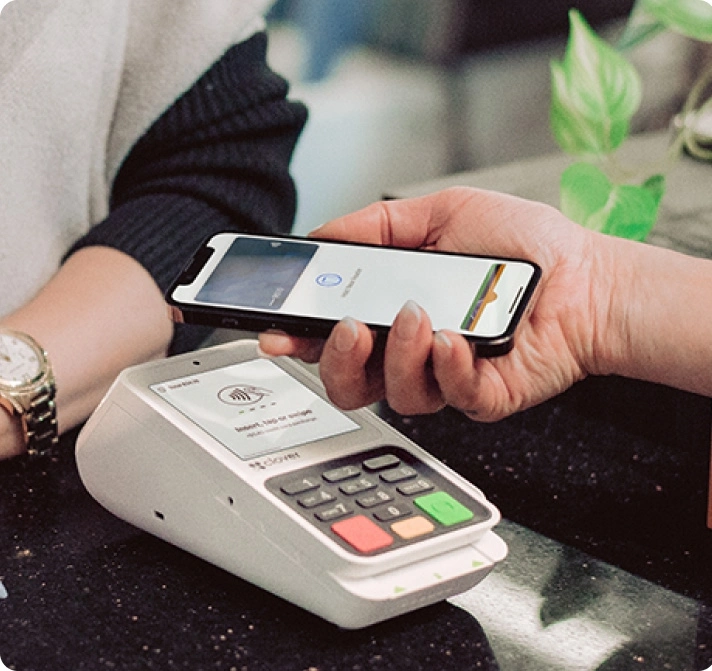
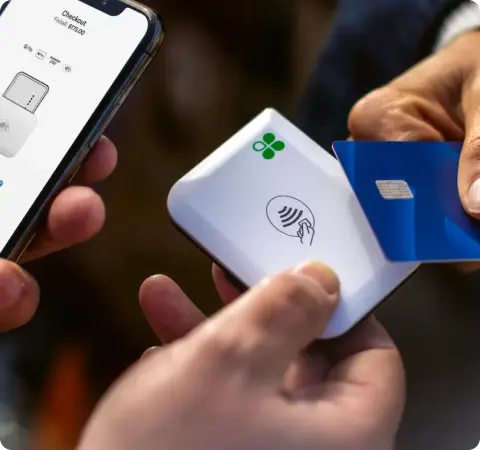
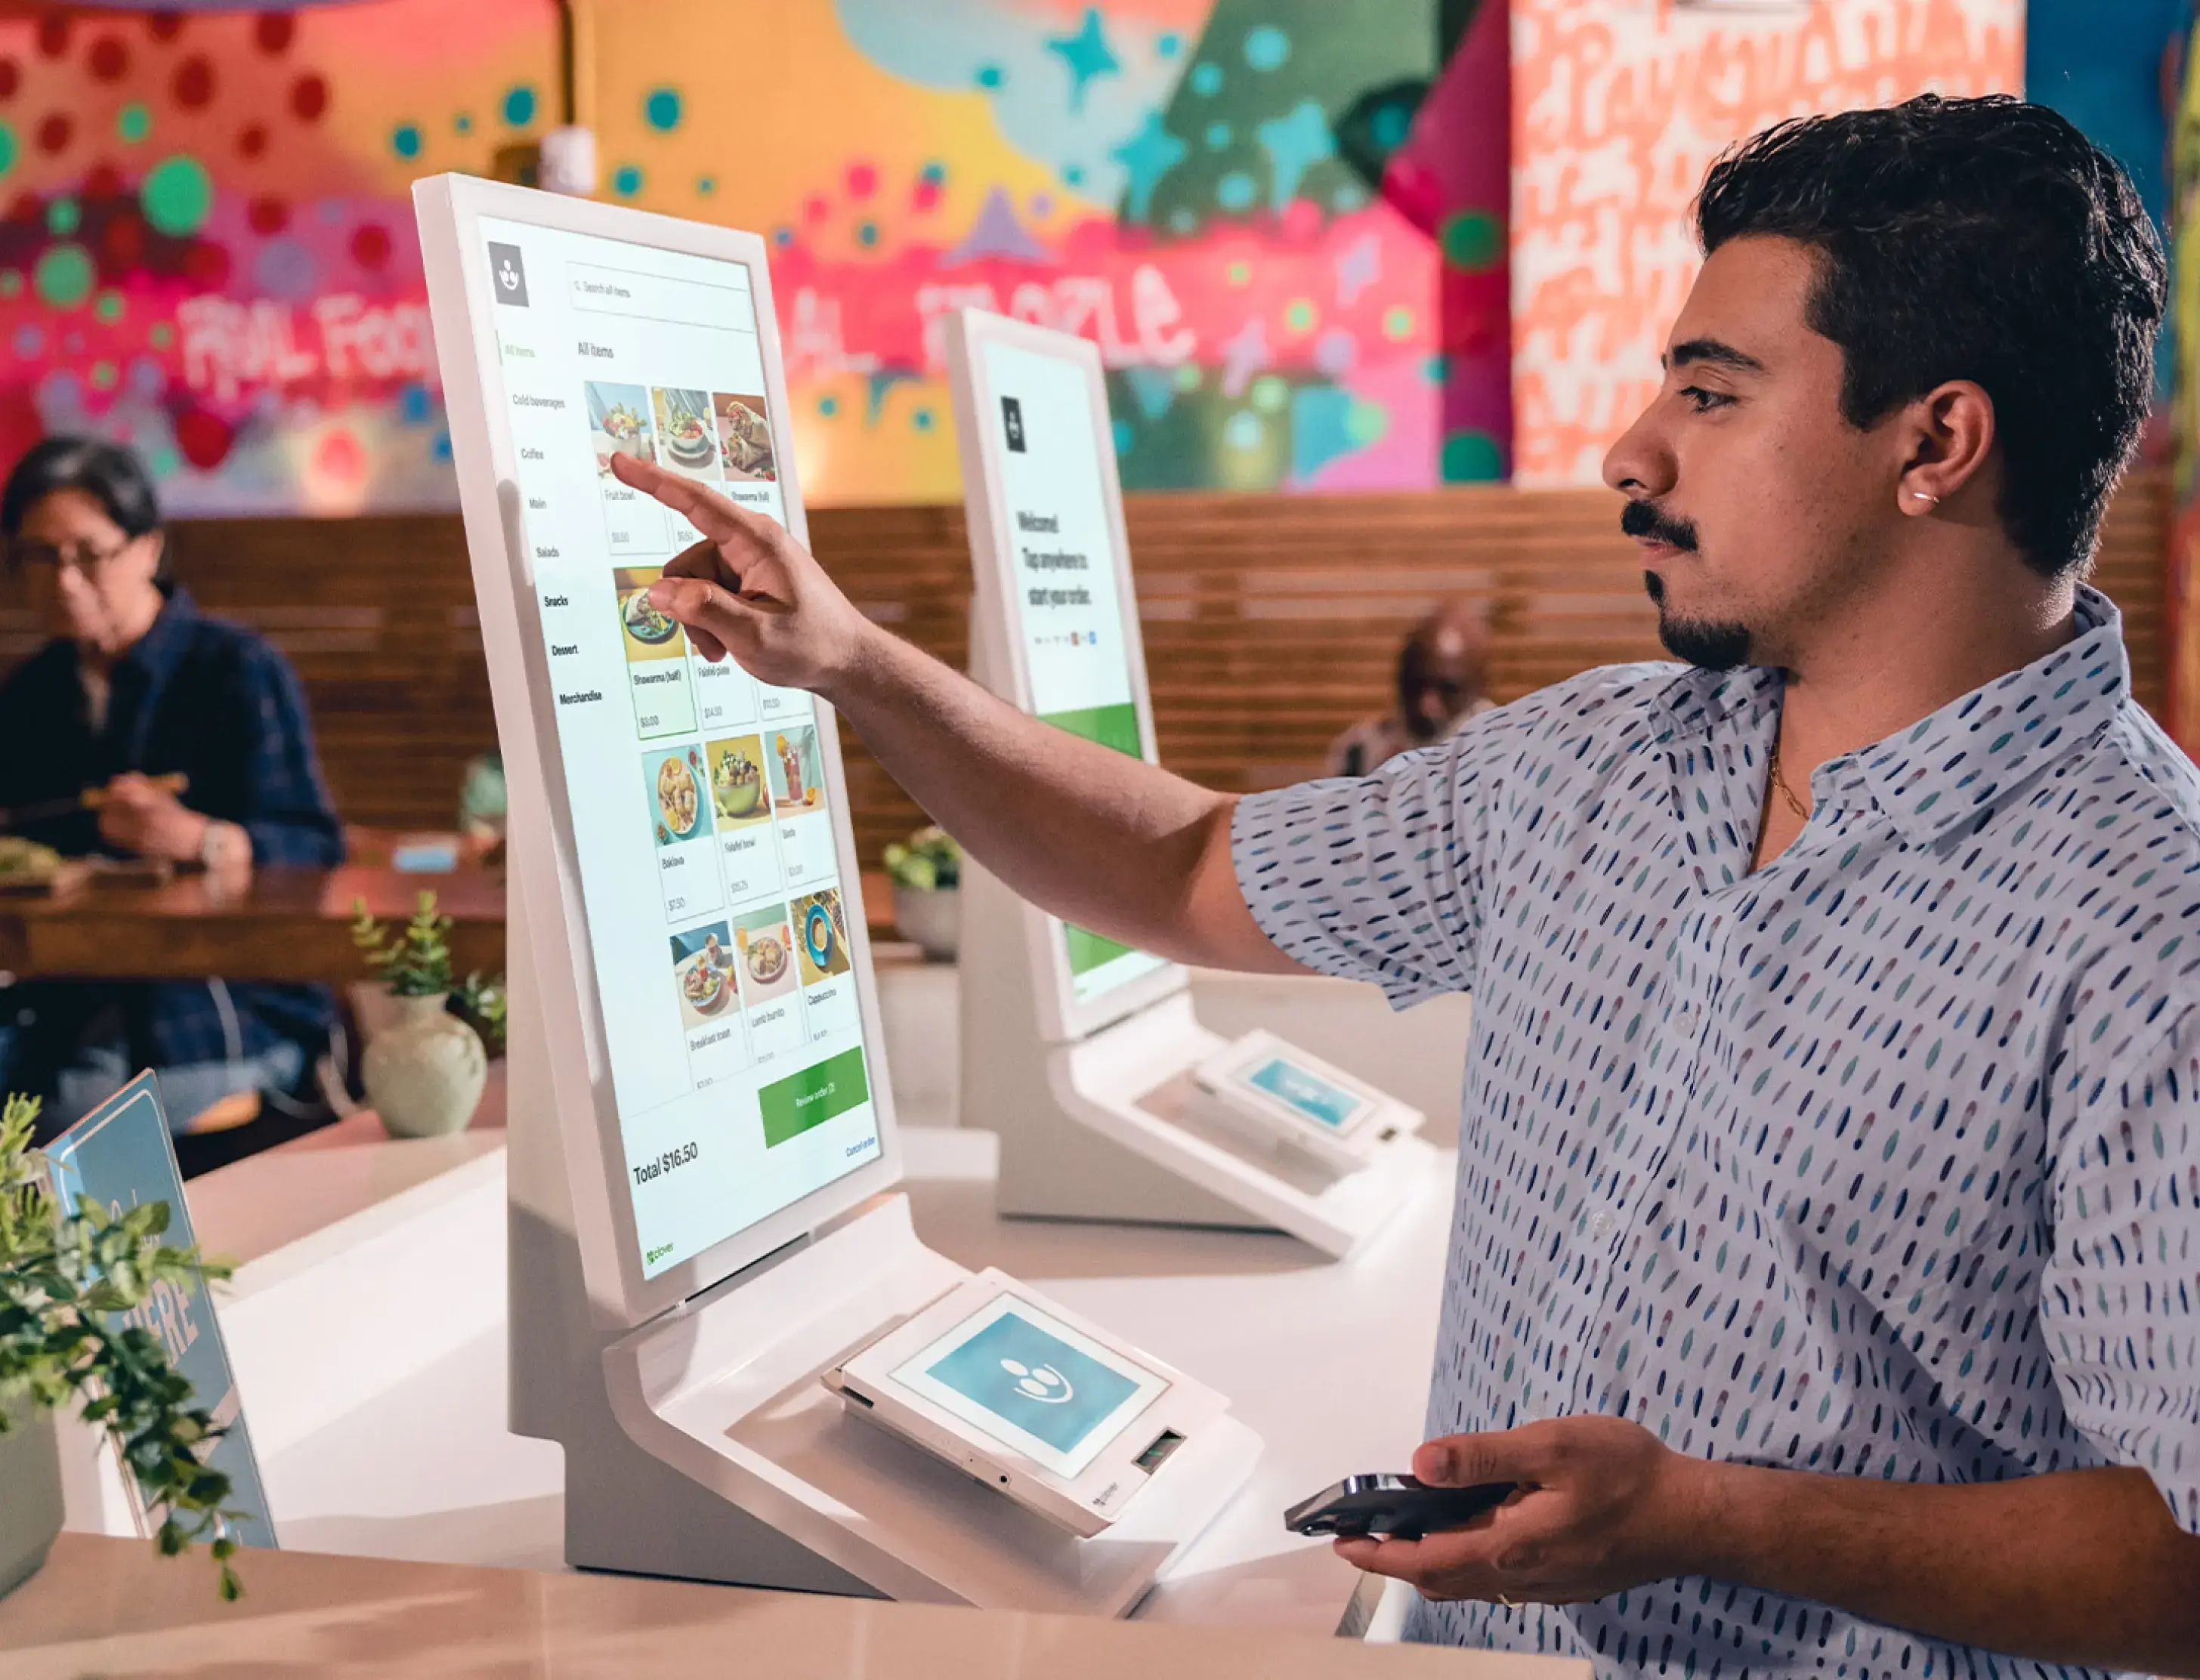
Which device, in one line each
Most businesses end up with a combination — a station at the counter and a handheld for the floor. Because the software is shared, nothing is relearned and inventory stays in one place.
The hardware is the easy part
Built from your menu, not a template
We load your items, modifiers, categories and tax rules before the device arrives, so day one is trading rather than data entry.
Set up inside the checkout flow
Cash and card prices, card-type detection so debit is handled correctly, receipt wording and the signage — configured on the device, not left to staff.
Only the ones you will use
The Clover app market runs to hundreds of add-ons with monthly fees attached. We recommend the few that earn their subscription and skip the rest.
No end-of-life hardware
Earlier Clover generations are phasing out of app updates. We place current devices only, and tell you where an existing unit stands.
Not sure which device fits?
Tell us how orders arrive and where payment happens. We will name the device, the accessories you actually need, and the ones you do not.
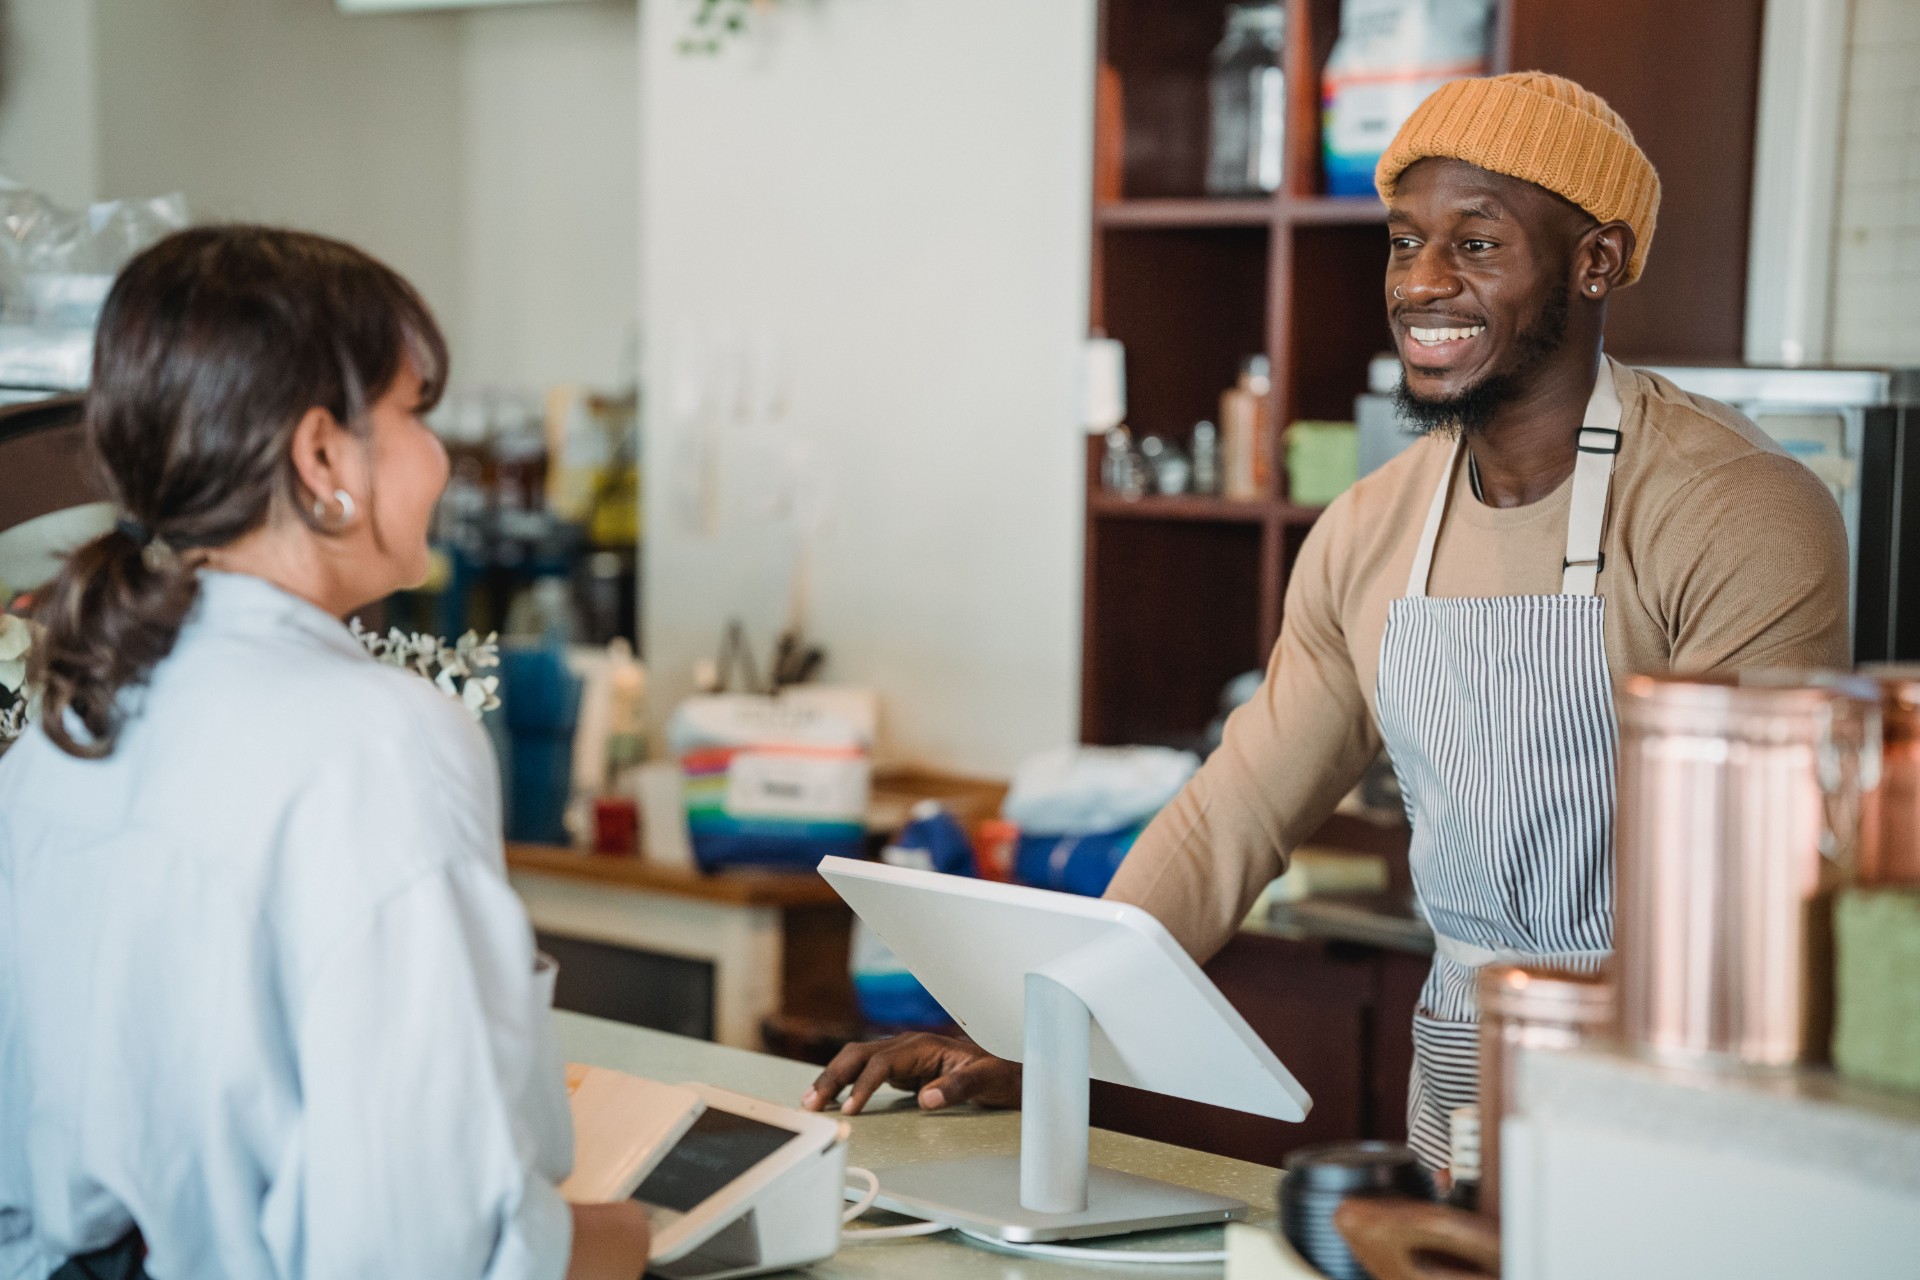
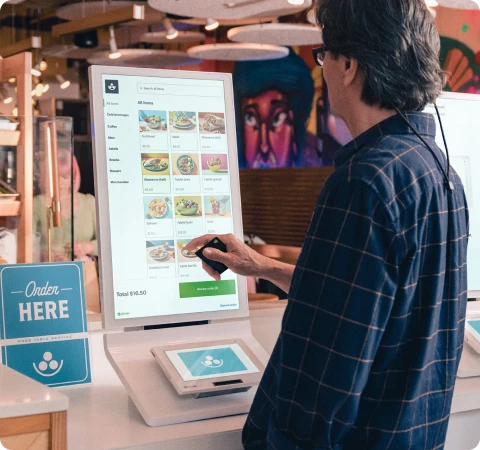
Four steps, and you can stop after any of them
Four places a specialist saves you real money
Reading what you are actually charged
Effective rate, downgrades, padded assessments, equipment leases you forgot signing. We line-item it before we quote anything.
Qualifying at the right category
Card-present versus keyed, level-2 data on commercial cards, ticket size and AVS habits. Small changes at the terminal move the effective rate more than a headline discount does.
The right terminal, not the one in stock
We are not tied to one manufacturer, so the recommendation follows your counter, your connectivity and your pricing program — and often keeps hardware you already own.
PCI and disclosure, done once
We complete the PCI questionnaire with you, and keep your pricing displays, receipts and signage inside card-brand rules as those rules change.
The largest single saving available to most merchants
Rate shopping trims basis points. Moving the card fee to the customer who chooses to pay by card removes most of the cost line altogether — which is why we model it for every business we review. We check eligibility by state and card type, pick dual pricing or surcharging based on your average ticket and customer mix, configure the terminal or POS, write the receipt wording, and supply the signage. Where it would cost you customers, we say so and leave it alone.
Thank you — your email is ready to send.
Submit another request
Thank you — we will be in touch.
Submit another application
Partner programs customized to the book you actually have
Wherever you are on your payments journey, you should expect high-touch service and pricing that holds up under comparison. New to merchant services or running a full-service portfolio, we build the program around the needs you have now — and leave room for it to grow.
A turnkey solution for however your merchant operates
The whole ecosystem is yours to quote — software, hardware, banking and payroll on one account. When a merchant grows into something new, you do not have to hand them to someone else.
Offices, agents and dealers
Bring one deal a quarter or a book of two hundred — the program is the same, the split scales with volume.
Send us your current schedule.
We will come back with your split on this program, side by side with what you earn today.
Why we do it
What we enjoy most is the relationships — with merchants and with the agents who serve them. Building programs that let an agent earn a real living, and finding technology that takes friction out of how a business actually operates, is the part of this job we would do anyway.
Between us we have decades in payments and very little interest in coasting on it. We are honest, we work hard, and we keep learning as the industry moves — because the answer that was right five years ago usually is not the right one now.
And we wanted a company where support means a real person. You get a name and a number, not a ticket in a queue — someone who knows your account before you finish explaining it.
Residuals
Paid monthly for as long as the merchant processes, with statements you can audit.
We do the work
Statement review, proposal, install and training. You stay the trusted partner.
Your client stays yours
We work through you, not past you — every recommendation comes to you first.
Who this works best for
Anyone whose clients already trust them with money decisions. One introduction a quarter is enough to make it worthwhile.
Apply to partner